

Quick note on terms, in case you need it: offcase arguments are the negative positions that aren’t direct attacks on your advantages — disadvantages, counterplans, kritiks. A disadvantage is a bad thing the plan causes. The negative reads it in the 1NC, the affirmative answers it in the 2AC, and whoever explains the chain better in the last two speeches usually wins it.
This packet is available here for free from the National Debate Coaches Association. I also added them to the DebateUS files so subscribers can easily access them.
VOCABULARY. This file runs on financial and macroeconomic terminology that novices are unlikely to have seen. A long list is at the bottom.
1. How a Disadvantage Works
Every disadvantage is a chain with four parts. Learn them in this order, because it’s the order they get read and the order they get attacked.
Uniqueness — the bad thing isn’t already happening, and won’t happen unless the plan passes. Here, the uniqueness card says the U.S. economy is strong right now. If the economy were already collapsing, the plan wouldn’t be responsible for the collapse. Uniqueness is the most-skipped part of a disadvantage and often the most vulnerable.
Link — the plan causes the thing. Here, the plan eliminates the private health insurance industry, which wipes out its stock value. Two separate questions live inside every link, and you should learn to distinguish them now: link direction asks whether the plan pushes this way or the opposite way, and link magnitude asks how hard it pushes. An affirmative can lose the direction fight and still win by making the push small.
Internal link — the steps between the plan’s effect and the final impact. Here there are two: a stock market collapse causes a recession, and a U.S. recession spreads to the global economy. Each internal link is separately attackable, which is why you should name them separately on your flow rather than lumping them together as “the impact.”
Impact — the final harm, and the reason the judge should care about it more than about the affirmative’s advantages. Here, world war.
This disadvantage has no explicit brink — no card saying how big a market decline has to be before a recession follows. Some disadvantages have one; when they don’t, that absence is an argument.
The rule that organizes everything below: the negative needs every part of the chain, and the affirmative needs to break only one. But breaking one link reduces the risk rather than eliminating it, unless the affirmative wins it completely — which is why affirmatives can’t survive on defense alone and need at least one argument that gives them offense.
2. The Big Picture: What the Stock Market Has to Do With Health Insurance
The chain here only makes sense if you understand one fact about single payer: it doesn’t regulate the private health insurance industry, it abolishes it.
Under single payer, the federal government becomes the only payer for covered services. Private insurers are prohibited from selling coverage that duplicates the government plan. What’s left is a small supplemental market — cosmetic surgery, adult orthodontics, things the federal plan excludes. Companies like UnitedHealth Group make nearly all their revenue from exactly the business the plan bans.
Those companies are publicly traded, which means ordinary people own them. Market capitalization is the total value of a company’s outstanding shares — share price times number of shares. When a company’s business is outlawed, its market capitalization falls toward zero, and whoever owned those shares loses that money. Health insurance shares aren’t mostly held by a handful of tycoons; over 90% of outstanding shares in these companies are institutionally owned, meaning they sit inside the mutual funds, index funds, and ETFs that hold most Americans’ retirement savings.
Three more concepts make the rest legible.
The Takings Clause. The Fifth Amendment says “nor shall private property be taken for public use, without just compensation.” If the government destroys the value of your property by taking it for public use, it may owe you money. This cuts both ways in this debate, which is what makes it interesting: the negative uses it to say the plan carries an enormous compensation bill, and the affirmative uses it to say shareholders get paid and therefore aren’t wiped out.
The wealth effect. When people’s investments lose value, they feel poorer and spend less, even if their income hasn’t changed. Since consumer spending is roughly two-thirds of U.S. GDP, a large enough hit to household wealth can drag down the whole economy. This is the mechanism connecting a stock market decline to a recession.
Sector-specific versus economy-wide shocks. A crash confined to one industry behaves differently from a crash that hits everything. Hold onto this distinction — it turns out to be the single most important idea in the affirmative’s answers, and it’s buried in a card most novices skim past.
One last piece of context. Health care is about 18% of GDP, and 20 of the 100 largest companies in the S&P 500 by market cap are healthcare firms. That’s why the negative argues a shock to health insurance doesn’t stay in health insurance.
3. The Stock Market Disadvantage in One Paragraph
The U.S. economy is doing well right now — strong labor market, resilient consumer spending, a boom in AI investment. Single payer would abolish the private health insurance industry, destroying hundreds of billions of dollars in shareholder value held largely inside ordinary Americans’ retirement accounts, triggering a constitutional obligation to compensate those shareholders that the government can’t afford, an explosion of litigation, and the loss of over a million jobs. That shock spreads to pharmaceutical, hospital, and medical device stocks, and the precedent — the federal government deliberately destroying an entire industry — shatters investor confidence in every other regulated sector. The resulting market collapse wipes out household wealth on a scale that produces a severe recession, the U.S. recession becomes a global recession, and global economic crisis produces the nationalism, protectionism, and great-power confrontation that historically ends in world war.
If you can’t retell that in four sentences, read it again before moving on.
4. The 1NC Shell, Card by Card
Four cards. Here’s what each one does and what to take from it.
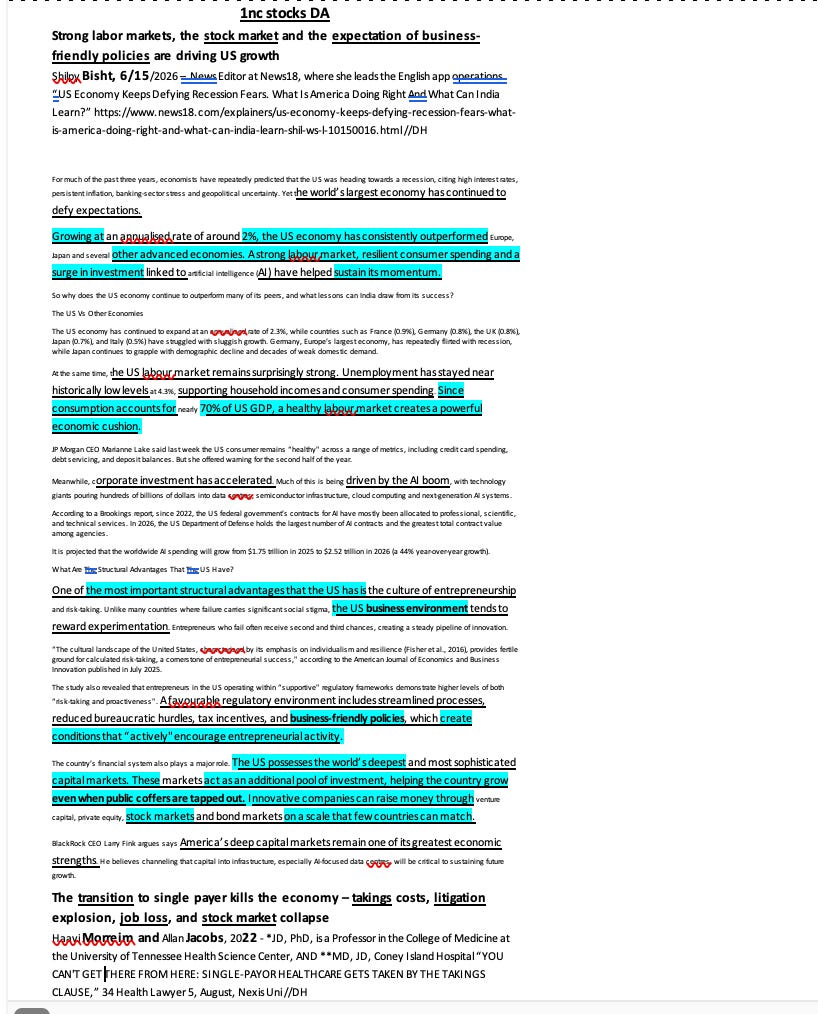
The uniqueness — Bisht 6/15/2026. The U.S. economy keeps defying recession predictions. Growth is running at an annualized 2.3% while France, Germany, the UK, Japan, and Italy are all under 1%. Unemployment sits near historic lows at 4.3%, and since consumption is nearly 70% of GDP, a healthy labor market is a powerful cushion. Corporate investment has accelerated, driven by the AI boom — worldwide AI spending is projected to grow from $1.75 trillion in 2025 to $2.52 trillion in 2026. The card credits America’s deep capital markets and business-friendly regulatory environment.
The link — Morreim and Jacobs 2022. A law review article in The Health Lawyer. Their hypothetical publicly traded health insurer has a market capitalization near $400 billion and bond debt around $40 billion. If single payer drops that value to zero, the Takings doctrine requires compensation, and adding up all the shareholders and bondholders across the industry, the compensation figure approaches 5.6% of GDP. Then add the “likely-seismic ramifications throughout the rest of the markets,” the litigation costs, and the abrupt termination of over a million health insurer employees plus the people who work in coding, billing, precertification, and appeals. The card explains why other countries didn’t face this: they built universal coverage early, before developing a robust private equity market in health insurance. America built the market first, and single payer would destroy it.
The internal link — Gopinath 2025. Gita Gopinath is a Harvard economist and former chief economist of the IMF, writing in The Economist. Her numbers are the strongest in the file. A correction the size of the dotcom crash could wipe out over $20 trillion in American household wealth — roughly 70% of 2024 GDP — several times the losses of the early 2000s. That would cut consumption growth by 3.5 percentage points and take two percentage points off GDP growth before counting declines in investment. Foreign investors could lose over $15 trillion, about 20% of the rest of the world’s GDP, against roughly $2 trillion in the dotcom crash. And the usual cushion may not be there: the dollar hasn’t been behaving like a safe haven, government debt is at record highs limiting fiscal stimulus, and tariff escalation adds further risk.
The impact — Lesser 2025. German Marshall Fund. The world has been here before: in the decade before World War I, fear of relative economic decline drove strategic instability even amid high interdependence. During the interwar years virtually every major power had a ministry of economic warfare. Three developments worry him — the slide from crisis to war can be rapid, as in 1914 when the European security order collapsed in weeks; declining interdependence is destabilizing in itself, because states that believe they have nothing to lose behave differently in a crisis; and economic crises fuel radical ideologies and the collapse of the political center, as in the 1930s. His line: “2025 begins to look disturbingly like 1935.”
Coaching verdict. Gopinath is the best card in the file by a wide margin — a genuinely elite author, quantified, recent, and published somewhere serious. The link card is the weakest part of the shell despite being the most important, and for a reason novices won’t spot on their own: it is a Takings law article, not an economics article, and it says so. More on that in section 10. The impact card is about trade wars and export controls, and the connection from an equity crash to economic warfare between great powers is a step the card doesn’t take.
5. Reading It in the 1NC
This shell is four cards and will run roughly three to four minutes fully highlighted, which fits comfortably in a novice 1NC alongside case answers.
Read all four. If you must cut, trim the inside of Bisht and Lesser rather than dropping either card — you cannot drop uniqueness and you cannot drop the impact, or you have no disadvantage. Gopinath is untouchable; her numbers are the position.
Tag the parts out loud. Say “uniqueness,” “link,” “internal link,” “impact” as you go. Judges flow disadvantages in that order, and a novice negative who reads four cards without labeling them makes the 2AC’s job easier, because the affirmative gets to decide what each card was for.
In cross-examination, ask one question: does the plan compensate health insurance shareholders? You win either answer, and you should know why before you ask. If they say no, you get the full link — investors are wiped out with no cushion, which is Epstein’s argument. If they say yes, you get the cost argument and the precedent argument — the government is spending an enormous sum to buy an industry it’s shutting down, and every other regulated industry is watching. Do not let them answer “that’s not in the plan text” without following up on what normal means would do, because their whole third answer depends on the buyout being normal means.
6. How the Affirmative Answers It
This file includes an affirmative section, so you know exactly what the 2AC will be. Six arguments. I’ll walk them in order, name what each one is doing on the flow, and then add the answers the file leaves out.
1. Non-unique — a crash and recession are coming anyway (Sor 2026). Gary Shilling predicts a recession this year and an S&P decline of as much as 30% by year end. The Shiller CAPE ratio is at its highest since before the dotcom crash; price-to-sales and price-to-book are at all-time highs. Broader capital expenditure grew just 3.9% at the end of last year, down from over 24% during the pandemic. Real disposable income growth has slowed to 0.4%, its lowest in three years, and the personal savings rate is down to 3.6%.
What it does: attacks uniqueness. If the crash happens without the plan, the plan isn’t responsible for it.
2. No link — the industry adapts (Abelson and Sanger-Katz 2019). The New York Times piece the negative’s own file cites for “no precedent in American history” also says the companies “would most likely survive” because they have additional lines of business. And insurers might evolve into contractors for the government system — they already administer claims processing for Medicare. Aetna’s former CEO: “The government would have to build out infrastructure if they were to shut down all the private insurance companies.”
What it does: attacks link magnitude. Not “the plan doesn’t affect insurers” but “it doesn’t zero them out.”
3. No link — normal means is a buyout (Messman 2018). Buying out and dissolving the private insurers would cost roughly $700 billion at enterprise value and generate over $400 billion in annual administrative savings, funded with 10-year Treasuries at about $80 billion a year. The card explicitly notes that not buying them out would both damage ordinary Americans’ retirement savings and constitute a prohibited Fifth Amendment taking.
What it does: attacks the link by changing what the plan does. This is the strongest structural answer in the file, and note that it uses the negative’s own Takings argument as the reason a buyout happens.
4. No internal link — a market crash won’t cause a recession (Boughedda 2026, reporting Capital Economics). This is the affirmative’s best card and the sentence to memorize is this: “the causality almost always runs from the economy to markets rather than the reverse.” U.S. equity declines of 20% or more “often coincide with recessions but rarely or never cause them.” The damaging episodes — 1929, 2008 — saw stocks fall alongside an independently weakening economy. In 1946, 1962, and 1987 corrections had limited economic impact because the backdrop was stable and policymakers responded quickly. Capital Economics expects the S&P to fall 12.5% next year with “very limited economic consequences,” and says even a 20–30% correction “need not cause a recession in isolation.”
What it does: attacks the first internal link, which is where this disadvantage is weakest.
5. Turn — single payer creates net job gains (Bivens 2020, EPI). Reform would boost wages by letting employers redirect health spending into pay, increase job quality, reduce the shock of job loss, support self-employment and small business formation, reduce “job lock,” and produce a net increase in jobs as public spending boosts aggregate demand, with losses in insurance and billing administration outweighed by gains in care provision and long-term care. The scale point matters: displaced insurance and billing workers amount to one-twelfth the size of economy-wide layoffs in 2018.
What it does: offense. This is the only argument in the 2AC that gives the affirmative a reason to prefer the plan rather than merely a reason the disadvantage is small.
6. No impact — recessions are part of the business cycle (McKinsey 2025). Recessions are caused by market imbalances and are essentially inevitable over time; another one is guaranteed sooner or later.
What it does: impact defense, and it’s thin. It establishes recessions recur, not that they don’t cause wars.
What the file leaves out — add these
Uniqueness overwhelms the link, and the negative’s own cards prove it. Bisht attributes current growth to the AI investment boom. Gopinath’s entire card is that the AI-fueled rally looks like 1999 and may be setting up a crash. So the negative’s uniqueness depends on the very thing their internal link says is a bubble. Say it plainly: if a dotcom-scale correction is already in the pipeline from AI valuations, a health insurance sector repricing is noise inside a much larger event the plan didn’t cause.
No brink. Nothing in this file says how much market decline triggers a recession. Gopinath models a dotcom-magnitude crash; the health insurance sector is a fraction of that. The negative never bridges the gap between “insurers lose their value” and “the market falls far enough to matter.”
Alt causes, all named in the negative’s own internal link. Gopinath lists tariff escalation, Chinese critical-mineral export controls, doubts about Federal Reserve independence, dollar weakness, and record government debt limiting fiscal response. Those are her risk factors, not the plan’s.
The Fed exists. The negative’s 70-years-of-data card is conditioned — Farmer’s finding is that a big crash produces a recession “in the absence of central bank intervention.” Central banks intervened in 1987, in 2008, and in 2020. Read the qualifier out loud; it’s in their card.
Sector-specific shocks don’t cause recessions. This is the best argument available to the affirmative and it’s in a 1AR card most novices never get to. McKeown’s study of ten bear markets since 1920 produces eight consistent findings, and the eighth is that “the cause of the correction is important — economy-wide shocks are much worse than sector-specific ones.” A health insurance shock is definitionally sector-specific. Move this into the 2AC.
Timeframe. Whatever the affirmative’s advantage is, compare arrival times. Coverage losses and deaths from the status quo are annual and immediate; the disadvantage requires an equity decline, then a wealth effect, then a recession, then global transmission, then great-power confrontation.
The trap — do not double turn yourself
The most damaging thing a novice can do on a disadvantage is read a link turn and an impact turn together, because the combination argues that the plan prevents something good. Here the specific danger is arguments 2 and 5.
Argument 2 says private insurers survive and adapt, so the link is small. Argument 5 says eliminating insurance and billing jobs is good for the economy because the gains elsewhere outweigh. Read carelessly, those become: the industry survives and destroying the industry is beneficial. A competent 2NR will stand up and say pick one — if insurers survive, you don’t get the efficiency and jobs benefits you’re claiming; if they don’t survive, you have conceded the link.
The fix is a sentence, and you should write it into your 2AC now: the insurance industry’s administrative function is eliminated while the firms themselves survive in supplemental and contracting roles. That’s coherent, it’s what Abelson and Sanger-Katz actually say, and it preserves both arguments. Say it that way and the double turn never materializes.
Two other common failures worth naming. Do not go for impact defense alone against a world war impact — McKinsey saying recessions recur is not a reason a recession doesn’t cause war, and a negative will happily grant it. And do not drop uniqueness because it looks like the boring card; against this disadvantage it is one of the two best places to attack.
7. Rebuilding in the Block
You are the negative again. Here is how the file answers each 2AC argument, and where to spend your time.
Against non-unique. Four cards saying fundamentals are strong: market fundamentals will drive record highs, long-term healthcare fundamentals are driving investment, all long-term economic fundamentals are positive, and growth is high and increasing. This is a card-dumping block and it works fine, but the better argument is analytic — a predicted correction from overvaluation is not the same event as a government-caused destruction of an industry, and their own Shilling card says the only things that could prevent a downturn are fiscal stimulus or consumer strength. Note that Shilling forecasts a 20–30% decline, which is exactly what Capital Economics says need not cause a recession. Their uniqueness answer and their internal link answer are in tension, and you should point that out.
Against adaptation. Morreim and Jacobs again: a supplemental market for cosmetic surgery and over-the-counter medications faces obvious moral hazard — people won’t buy coverage for things they don’t plan to use, and if they do plan to use them, the insurance costs as much as the procedure. Such a market “would hardly sustain an enormous firm.” Then Speights for the ripple: 20 of the top 100 S&P 500 companies by market cap are healthcare, drug prices would fall at least 30% under Medicare for All, and one JAMA analysis projected a $151 billion national loss across 5,262 community hospitals.
Against the buyout. You have three cards, and you should be selective, because one of them hurts you. Epstein says trillions get drained and shareholders can’t count on compensation because the government could never raise enough. Caird says if the government can wipe out one industry, hospital, drug, medical supply, and equipment stocks all follow, and the crash lands somewhere between 1929 and 2008.
Do not read Phillips for magnitude. Phillips is in this block, and buried in it is the single most damaging sentence in the negative file: “If the entire health insurance market capitalization were to disappear, it would not drop the S&P 500 by a drastic amount.” Phillips puts aggregate publicly traded health insurance market cap at about $600 billion — roughly Facebook-sized, smaller than Apple or Microsoft. Read Phillips only for the second half: that a buyout would be “an act of eminent domain unprecedented in American history,” an overreach of government power greater than making healthcare a public good, and that the secondary and tertiary effects are what matter. If you read the whole card you have handed the affirmative their magnitude answer.
The strategic consequence: argue precedent and investor confidence, not affordability. Affordability is where the affirmative has real numbers — Diaz-Alvarez prices a buyout at $240 billion with an 18-month payback and cites British postwar nationalization, Canadian potash, New Zealand railroads, and Swedish ore as precedent. You will not win that the government can’t write the check. You can win that writing it announces to every investor in every regulated industry that Washington will destroy a sector when it disapproves of it.
Against “a crash won’t cause a recession.” This is your strongest block and where the 2NR should live. Carlson: 62% of households own stocks today versus 25% in 1987, stocks are 36% of household financial assets — the highest in records going back to the 1950s, and the top 10% own nearly 90% of the market. Jayakumar: personal consumption is about 67% of GDP and those earning over $250,000 now account for nearly 50% of all U.S. consumer spending, up from a third in the 1990s, so the wealth effect from an equity decline is far larger than in previous cycles. Merrefield: Farmer’s Oxford Bulletin study found a big crash is followed by a major recession one to four quarters later, and the relationship has been structurally stable for seventy years.
The framing that ties it together, and it’s in the file notes: today’s market is a unique moment. More money is invested than at any point in history, so a crash now is more catastrophic than the historical episodes the affirmative cites.
Against the jobs turn. Summers argues the plan is on balance worse — large labor market effects, discouraged hiring particularly of low-skilled workers, dulled incentives to take jobs, and a market decline that falls more than proportionally to earnings. Adams: healthcare is 20% of GDP and “our economic success as a nation is predicated on this market-based healthcare delivery system.” Wainer: over the past year the U.S. added 156,000 jobs while healthcare alone added 375,000 — strip out healthcare and the rest of the economy is losing jobs.
Be careful with Wainer. The card’s actual thesis is that healthcare employment growth comes from an aging population, is concentrated in home care and outpatient settings, and — in the card’s own words — healthcare jobs and health insurance coverage “need not move in tandem.” It also says health insurers specifically face structural pressure from Washington. Read it for the topline jobs number and expect the affirmative to read the rest back at you.
Against no impact. Väyrynen concedes that an economic crisis doesn’t always produce military confrontation but argues that a deep enough crisis makes it unavoidable, as between the world wars. Vision of Humanity reports that the WEF’s Global Risks Perception Survey 2026, polling over 1,300 experts, now ranks “geoeconomic confrontation” as the leading threat to world peacefulness, ahead of traditional warfare and extreme weather. Then Poast and Jiang for the great-power mechanism.
What to concede. Concede that recessions recur. Concede that a buyout is affordable. Neither costs you the disadvantage if you’re winning that this crash is different in kind — government-caused, precedent-setting, landing on a market where household exposure is at an all-time high.
8. Impact Calculus — Why It Outweighs the Case
Novices lose disadvantages they were winning because they never explain why the disadvantage matters more than the affirmative’s advantages. Do this work in the 2NR explicitly.
Turns case, and this is the highest-value card in the file. Baker argues an economic downturn turns the affirmative — because everyone depends on a single national payer, budget squeezes produce system-wide effects. UK austerity after 2010 produced NHS underfunding, staffing crises, and record waiting times; Canadian provinces have repeatedly frozen physician fees and hospital budgets during downturns. A recession means the plan gets underfunded, so the affirmative doesn’t even get its own advantage. This is worth more than any impact card because it makes the disadvantage a reason the plan fails rather than merely a cost of the plan. Most novices skip it. Don’t.
Magnitude. Gopinath’s $20 trillion in household wealth is roughly 70% of U.S. GDP, and $15 trillion in foreign losses is about 20% of the rest of the world’s output. Then the impact is global war.
Probability. Your honest best framing is Väyrynen plus the WEF survey: you don’t need every recession to cause a war, you need a deep enough one, and 1,300 experts now rank geoeconomic confrontation as the leading threat to peace. Do not overclaim here — Lesser himself says an obsession with economic warfare doesn’t lead inevitably to war.
Timeframe. This is your weak axis and you should acknowledge it rather than pretend. The disadvantage runs through a market decline, a wealth effect, a recession, global transmission, and then great-power confrontation. The affirmative’s harms are annual. Your answer is the turns-case argument, which arrives on the same timeline as their solvency: the plan passes, the economy contracts, the system is underfunded from the start.
Reversibility. Recessions end; a world war doesn’t unwind. Use it, briefly.
9. Which Affirmatives It Links To
The file is unusually clear about this and you should follow it: this disadvantage links only to the single payer affirmative. Do not read it against the ACA affirmative.
The reason is the link. Every card in the shell depends on the elimination of the private health insurance industry. An affirmative that expands subsidies, extends eligibility, or adds a public option leaves insurers in business — several of them do more business under those plans, not less. Reading this against an ACA expansion aff means reading a link card about abolishing an industry against a plan that subsidizes it, and a competent 2AC will simply point that out and move on.
So: read it against single payer, Medicare for All, and anything that prohibits private duplicative coverage. Do not read it against ACA subsidy expansion, Medicaid expansion, a public option, or a plan that caps provider payment rates without touching who sells insurance.
If you’re affirmative on single payer, expect this position in most rounds. The file notes call it “probably the strongest negative argument against single payer,” and that assessment is fair.
10. Analytics Against the Disadvantage — And How the Negative Answers
An analytic is an argument made without a card, from logic or from the negative’s own evidence. Analytics decide novice rounds because you can generate them in prep while the other team can only read what’s already in their file. Every entry has to finish the thought — a question is not an argument.
Against the Uniqueness
The uniqueness card and the internal link card contradict each other. Bisht credits current U.S. strength to accelerating corporate investment driven by the AI boom. Gopinath’s card is a warning that the AI-fueled rally resembles the exuberance that culminated in the dotcom crash. So the negative’s proof that the economy is healthy is the same phenomenon their internal link identifies as a bubble.
Neg answer: Uniqueness describes the economy as it stands; the internal link describes what a crash does once one occurs. Both can be true. But this reads badly out loud and the honest fix is to argue that AI investment is real productivity growth while a government-destroyed industry is a different kind of shock.
Bisht is a general-interest news explainer written for an Indian audience. The author is a News Editor at News18 and the article’s framing question is what India can learn from American growth. It is a summary of other people’s economics, not analysis, and it is doing the work of establishing that the U.S. economy is uniquely healthy.
Neg answer: The underlying figures — 2.3% growth, 4.3% unemployment, consumption at 70% of GDP — are standard and uncontested. Concede the source and defend the numbers.
Against the Link
The link card’s own conclusion is that the plan cannot happen, which is a different argument than a disadvantage. Morreim and Jacobs end with “You can’t get there from here. Single-payor healthcare would almost certainly be taken by the Takings Clause.” That is a legal prediction that courts would block the plan or compel compensation — a plan-flaw or fiat argument, not a forecast of economic collapse. And the compensation half undermines the negative’s own story: if the Takings doctrine requires the government to pay shareholders the difference, then shareholders are made whole, which is the affirmative’s buyout answer stated by the negative’s link card.
Neg answer: The disadvantage is the cost of that compensation — 5.6% of GDP — plus the litigation to establish it, plus the precedent. The card gives you the mechanism and the price tag; you’re not claiming investors go uncompensated, you’re claiming compensation is ruinous. This is a real answer, but it means the negative has to fight on the ground where the affirmative has Diaz-Alvarez and Messman.
The link card explicitly disclaims economic analysis. Read the sentence: “This article is indifferent to all of these questions,” listing whether single payer improves outcomes, whether providers exit, and how far taxes rise. It is a Takings law article. Its entire treatment of market effects is one clause about “likely-seismic ramifications throughout the rest of the markets,” with no evidence and no mechanism.
Neg answer: The card establishes the magnitude of the property destruction, which is what a link card has to do. Gopinath supplies the economics. Fair, but it means the negative has no plan-specific evidence that the shock propagates — only a law professor’s aside.
The three magnitude estimates in the negative’s own file differ by an order of magnitude. Morreim and Jacobs say compensation approaches 5.6% of GDP, roughly $1.6 trillion. Epstein says trillions get drained. Phillips says the aggregate publicly traded health insurance market cap is about $600 billion and that its total disappearance “would not drop the S&P 500 by a drastic amount.” Those cannot all be right, and the smallest number comes attached to a concession that the direct market effect is modest.
Neg answer: The estimates measure different things — Phillips counts only publicly traded equity and excludes Blue Cross Blue Shield and other non-public insurers; Morreim and Jacobs count stock plus bonds across the industry plus litigation. Use the spread to argue the floor is $600 billion and the ceiling is far higher. This is the best available answer and it’s still a concession.
Phillips’ concession is dispositive on the direct link. Facebook-sized. Smaller than Apple. If the entire industry’s public equity vanished, the S&P doesn’t move dramatically. Everything the negative has left is “secondary and tertiary effects,” “spillover,” “precedent,” and “investor confidence” — the parts of the argument with the least evidence behind them.
Neg answer: Precedent is the argument, and it’s not a weak one — Caird’s point is that stock prices are based on investor confidence and the government demonstrating it will destroy a disfavored industry reprices risk across every regulated sector. But acknowledge you’re arguing about sentiment rather than about balance sheets.
Caird is a 2017 letter to the editor in a local newspaper. A former VA administrator writing opinion in the Eugene Register-Guard, and the card contains the sentence “It is impossible to estimate how much the stock market would tumble” immediately before estimating that it would tumble somewhere between 1929 and 2008.
Neg answer: Don’t defend it. Read Phillips for precedent instead and make the confidence argument analytically.
Speights is an investing blog. The Motley Fool, 2019. Useful for the fact that 20 of the top 100 S&P companies are healthcare, weak for anything causal.
Neg answer: Use it for the composition fact only.
Against the Internal Links
Farmer’s finding is conditioned and the negative reads past the condition. The card says a big crash “in the absence of central bank intervention” is followed by a major recession. The Federal Reserve exists, has a mandate, and intervened in 1987, 2008, and 2020. McKeown’s parallel finding makes the same point from the other direction: macroeconomic effects are limited “when there is the will and scope to apply monetary and fiscal loosening.”
Neg answer: Gopinath addresses this — record government debt limits fiscal stimulus, and doubts about Fed independence undermine the credibility of monetary response. That’s a genuine answer and the negative should read it, because without it the Fed argument is close to a full internal link takeout.
A health insurance shock is sector-specific, and the negative has no answer to that specifically. McKeown’s eighth finding across ten bear markets since 1920: economy-wide shocks are much worse than sector-specific ones, given the potential for adverse feedback loops. The negative’s blocks answer “crashes don’t cause recessions” in general. Nothing in the file answers the sector-specific point.
Neg answer: Argue the shock isn’t sector-specific because of the precedent mechanism — an industry destroyed by statute reprices political risk everywhere, which is economy-wide by definition. That answer is available analytically but it isn’t carded, and that gap is worth knowing about on both sides.
The negative’s own recession evidence identifies a mechanism that runs the wrong way. Carlson’s card is titled “Can the Stock Market Cause a Recession?” and its answer is a hedge: “No one knows if this wealth effect will show up for sure,” “it’s hard to say which one comes first,” and finally “the possibility is higher today than it’s ever been.” A claim about possibility being at a historic high is not a causal claim.
Neg answer: Jayakumar is the stronger card and does make the causal claim — the wealth effect’s magnitude has risen sharply post-pandemic and the top 10% now drive nearly half of consumer spending. Lead with Jayakumar and use Carlson for the ownership statistics only.
Against the Impact
The impact card is about tariffs and export controls, not equity prices. Lesser’s subject is economic warfare — sanctions, blockade, protectionism, decoupling, critical-mineral controls. Nothing in the card runs from “U.S. stocks fall” to “great powers wage economic war on each other.” The internal link between a market crash and geoeconomic confrontation is simply absent.
Neg answer: The bridge is that recessions produce protectionism and nationalism, which Poast supplies — a worsening economic outlook brings out nationalism, protectionism, and isolationism. Read Poast in the 1NC or be ready to explain the step, because the shell as written skips it.
Lesser hedges the conclusion. “None of this is meant to suggest that an obsession with economic warfare leads inevitably to conflict, much less global war.”
Neg answer: He follows it with “the odds of such a progression, already significant, have shortened considerably.” Read the next sentence.
Abdel-Fattah is a rhetorical exercise, not analysis. The card asks you to imagine waking up, checking your phone, and finding your coffee has tripled in price, and describes “a chilling, global economic winter, its icy grip felt in every home, on every continent, for generations.” There is no data and no mechanism.
Neg answer: Poast makes the same point with actual reasoning. Cut Abdel-Fattah.
Cross-Cutting
Count the chain. Insurance equity falls, the broader market falls, household wealth contracts, consumption drops, a recession begins, it transmits globally, protectionism and nationalism rise, great powers confront each other, war. Nine steps.
Neg answer: The affirmative’s advantages are equally long — single payer’s cost advantage runs healthcare spending to the debt to the defense budget to nuclear posture to nuclear war. And you have the turns-case card, which is two steps.
Summers is about Elizabeth Warren’s tax plan, not about single payer. His market estimate prices in a doubled billionaire wealth tax, a ban on fracking, energy industry reform, stepped-up financial regulation, a major antitrust expansion, and labor representatives on corporate boards. The plan does none of those things. He also concedes “accurate market predictions are impossible.”
Neg answer: The healthcare-specific piece survives — he separately cites a severe hit to health industry profits then running over $200 billion. Read that portion and leave the wealth tax analysis alone.
Nothing in the file establishes a brink. Gopinath models a dotcom-magnitude correction. Phillips says the sector is Facebook-sized. No card connects the size of the shock to the size of the market decline, which means the disadvantage asks the judge to assume that a $600 billion sector repricing produces a $20 trillion wealth destruction.
Neg answer: The precedent mechanism is what closes that gap — the direct loss is the trigger, not the magnitude. State it that way explicitly, because if the debate is about arithmetic you lose it.
The Five That Should Actually Worry the Negative
First, Phillips’ concession plus the magnitude spread. The negative’s own block card says the direct effect is small, and the file’s three estimates differ by an order of magnitude.
Second, sector-specific versus economy-wide. McKeown’s ten-episode study says sector shocks don’t cause recessions, and the file has no card answering it.
Third, the link card is a Takings law article that disclaims economic analysis and concludes the plan would be blocked. As written it is closer to a plan-flaw argument than a disadvantage.
Fourth, Farmer’s central bank qualifier. The negative’s seventy-years-of-data card excludes the exact condition that has obtained in every modern crash.
Fifth, the uniqueness/internal-link contradiction over AI. The negative’s healthy-economy card and its crash card describe the same phenomenon in opposite terms.
Everything else on this list is worth making, but those five decide rounds.
11. Gaps in the File — Know These Before Round One
For the negative:
No brink card. Nothing establishes how much decline triggers a recession. You will have to argue the precedent mechanism analytically.
No answer to sector-specific shocks. Your blocks answer the general claim that crashes don’t cause recessions. They do not answer McKeown’s finding that the cause of a correction determines its economic consequences. Prepare the “political risk repricing is economy-wide” analytic.
No answer to central bank intervention. Gopinath’s fiscal-space and Fed-independence lines are your only material, and they’re inside the 1NC internal link rather than in a block. Flag them when you read the card.
No card on the precedent claim from a credible source. The precedent argument is your best ground and your evidence for it is a letter to the editor and half of an actuarial blog post. Say it analytically and confidently rather than leaning on Caird.
For the affirmative:
Your only impact defense is McKinsey saying recessions recur. You have no card arguing economic decline doesn’t cause war, which is a real hole against Väyrynen and the WEF survey. Answer it with timeframe and with the case, not with impact defense.
Move McKeown into the 2AC. It’s filed as a 1AR extension and it’s the best card you have. Reading it in the 2AC gives you two speeches to explain the sector-specific finding.
Your buyout evidence is old. Diaz-Alvarez prices the industry from 2009 data, Messman from 2018, and both predate the market’s growth. Expect the negative to press that a buyout today costs far more than $240 billion, and be ready to argue the ratio — payback period and administrative savings — rather than the absolute figure.
Write the double-turn fix into your 2AC now. “The administrative function is eliminated; the firms survive in supplemental and contracting roles.” One sentence, and it protects arguments 2 and 5 from being turned against each other.
And know where the rest of your answers live. This DA links only to single payer, so if you’re reading the ACA affirmative you should never see it — but the Interest Rates DA, the Doctors DA, and the Pharma DA are separate files in the packet, and your answers to those are at the bottom of those files, not this one.
12. Vocabulary
Markets and Ownership
Stock (equity) — a share of ownership in a company. Owning stock means owning a fraction of the company’s future earnings.
Market capitalization — a company’s total value: share price times shares outstanding. When the negative says the health insurance industry is worth $600 billion, this is the measure.
Bond — a loan to a company. Bondholders get paid before shareholders if a company fails, which is why the link card counts bonds separately from stock.
S&P 500 — an index of 500 large U.S. companies, used as shorthand for “the market.” Twenty of its hundred largest members are healthcare firms.
Index fund / ETF / mutual fund — pooled investments that hold many stocks at once. Why this matters: over 90% of health insurance shares are institutionally owned, so the exposure sits inside ordinary retirement accounts rather than in a few wealthy portfolios.
Bear market — a decline of 20% or more in a major index. McKeown counts 18 of these for the S&P over the past century and analyzes ten.
Correction — a decline smaller than a bear market, usually 10% or more.
Valuation ratios — measures of whether stocks are expensive relative to fundamentals. The Shiller CAPE ratio (inflation-adjusted price-to-earnings) is the one to know; the affirmative’s non-unique card says it’s at its highest since before the dotcom crash, alongside record price-to-sales and price-to-book ratios.
Dotcom crash — the 2000–2002 collapse of internet stock valuations. Both sides use it as the reference event: Gopinath says a repeat would be far worse now, the affirmative says it produced only a mild recession.
Macroeconomics
GDP (gross domestic product) — total output of an economy. Healthcare is about 18% of U.S. GDP; the link card’s compensation figure is 5.6% of it.
Recession — a significant, broad, sustained decline in economic activity. Formally dated in the U.S. by the National Bureau of Economic Research.
Business cycle — the alternation of expansion and contraction. The affirmative’s impact defense is that recessions are a feature of this cycle rather than a catastrophe.
Consumer spending / personal consumption expenditure (PCE) — household purchases, and roughly 67–70% of U.S. GDP. Every version of this disadvantage runs through it.
The wealth effect — people spend more when their assets gain value and less when they lose it, independent of income. The mechanism connecting a market decline to a recession. Both sides agree it exists; they disagree about its size.
Marginal propensity to consume — the share of an additional dollar a household spends rather than saves. Lower for the wealthy, which is why it matters that the top 10% now drive nearly half of consumer spending.
Capital expenditure (capex) — business investment in equipment, facilities, and hiring. The affirmative’s non-unique card notes broader capex growth fell to 3.9% from a pandemic peak above 24%.
Aggregate demand — total demand for goods and services in an economy. The affirmative’s jobs turn argues public spending under the plan raises it.
Deindustrialization — the long-run decline of manufacturing as a share of employment and output. The negative uses it to argue the economy is fragile and shock-prone.
Overleveraged — carrying too much debt or too much exposure relative to the ability to absorb losses. The negative’s claim about household stock exposure.
Fiscal stimulus vs. monetary policy — fiscal is government spending and taxes; monetary is central bank action on interest rates and liquidity. Gopinath’s argument that there’s “less policy space” is a claim that both tools are constrained.
Lender of last resort — the central bank’s role supplying liquidity in a crisis. McKeown identifies willingness to play it as one of the eight factors determining whether a crash becomes a recession.
Soft landing — slowing an economy enough to control inflation without causing a recession.
Sovereign debt crisis — a government unable to service its borrowing. One of the affirmative’s inevitability scenarios.
Reserve currency — the currency other countries hold and trade in, which for now is the dollar. Its status is why a U.S. downturn transmits globally.
Flight to safety — investors moving into safe assets during a crisis, historically strengthening the dollar. Gopinath’s warning is that this cushion may not appear next time.
Geoeconomic confrontation — the weaponization of economic tools: tariffs, sanctions, investment controls, export restrictions. Now ranked by the WEF’s expert survey as the leading threat to world peacefulness, and the actual subject of the negative’s impact card.
Protectionism / decoupling — restricting trade; unwinding economic interdependence. The steps between recession and war in the negative’s story.
Law and Policy
Takings Clause — the Fifth Amendment provision that private property shall not be taken for public use without just compensation. The pivot of this entire disadvantage, and it cuts both ways: the negative uses it for the compensation bill, the affirmative uses it to argue shareholders get paid.
Eminent domain — the government’s power to take private property for public use with compensation. Phillips calls a health insurance buyout “an act of eminent domain unprecedented in American history.”
Buyout / nationalization — the government purchasing an industry rather than abolishing it uncompensated. The affirmative’s third answer, and the reason to ask about it in cross-x.
Enterprise value — a company’s total value including debt, not just equity. Messman’s $700 billion figure is measured this way, which is why it exceeds Phillips’ $600 billion equity-only figure.
TARP — the Troubled Asset Relief Program, the 2008 financial crisis bailout. The affirmative’s precedent that large government purchases of private financial assets happen and get repaid.
Moral hazard — when insurance changes behavior because someone else bears the cost. The negative’s argument that a supplemental market fails: nobody buys cosmetic surgery coverage unless they already plan to use it.
Medical loss ratio — the share of premiums an insurer spends on actual care rather than administration and profit. Diaz-Alvarez’s 81.5% figure against Medicare’s 98% is the administrative savings argument in one statistic.
Job lock — staying in a job for the health insurance. The affirmative’s jobs turn argues eliminating it makes labor markets more efficient.
Reading the Evidence
This disadvantage turns on a genuine methodological dispute, so these matter more than usual.
Correlation vs. causation — the central fight. Everyone agrees market crashes and recessions occur together. The question is which causes which, and McKeown states the affirmative’s position directly: “correlation does not necessarily imply causation.”
Causal direction — which way the arrow points. Capital Economics says causality “almost always runs from the economy to markets rather than the reverse.” If they’re right, the negative’s internal link is backwards.
Conditional finding — a result that holds only under stated circumstances. Farmer’s seventy-year relationship holds “in the absence of central bank intervention.” Always read the conditions on a card before you rely on it.
Sector-specific vs. economy-wide shock — whether a disturbance hits one industry or everything. McKeown finds this determines whether a correction has macroeconomic consequences, and it’s the affirmative’s best structural answer.
Projection vs. measurement — Gopinath’s $20 trillion is a modeled estimate of a hypothetical crash, not an observed figure. Shilling’s 30% decline is a forecast. Neither is data.
Base rate — how often something has happened historically. McKeown’s ten episodes since 1920 are a base rate; a single dramatic example is not.
Peer-reviewed vs. commentary — Farmer’s study appeared in the Oxford Bulletin of Economics and Statistics; Gopinath wrote a bylined invited essay in The Economist; Carlson and Caird wrote blog and newspaper opinion. Rank them out loud when it helps you.
The Organizations You’ll See Cited
Capital Economics — an independent macroeconomic research firm selling analysis to institutional clients. Not ideological, which is what makes McKeown the affirmative’s best card — the negative can’t dismiss it on source grounds and has to answer the substance.
Hoover Institution — conservative, Stanford. Epstein on the buyout.
Cato Institute — libertarian. Appears across the single payer negative files.
American Action Forum — center-right. The turns-case card, and also the rationing turn in the case file.
Economic Policy Institute (EPI) — progressive, labor-aligned. Bivens on jobs.
Physicians for a National Health Program (PNHP) — the physician advocacy organization for single payer. Quoted in the affirmative’s adaptation card.
German Marshall Fund — transatlantic policy institute, mainstream. Lesser.
Institute for Economics and Peace — publishes the Global Peace Index. The source behind the WEF risk survey card.
World Economic Forum — its Global Risks Perception Survey of 1,300+ experts is the negative’s probability evidence.
McKinsey & Company — management consultancy. The affirmative’s impact defense, and note it’s an explainer page rather than research.
Motley Fool — retail investing website. Speights.
Jacobin — socialist magazine. Diaz-Alvarez on the buyout, and worth knowing the outlet’s politics because the card is arguing nationalization would have been easy.
A Wealth of Common Sense — a wealth manager’s personal blog. Carlson.
The Health Lawyer — an American Bar Association health law publication. Morreim and Jacobs, and remembering that it’s a law journal is the key to the best analytic against the link.
Learn the four parts of the shell, then learn McKeown and the double-turn fix. That’s most of what decides this disadvantage in a novice round.